
AI in Insurance
Insurance AI market to hit $154b by 2034
The global artificial intelligence (AI) in insurance market is projected to grow from $13.45b in 2026 to $154.39b by 2034, according to data from Fortune Business Insights.
The industry was valued at $10.36b in 2025 and is expected to expand at a compound annual growth rate of 35.7% over the forecast period.
North America dominated the sector in 2025, accounting for 39.96% of the global market share due to widespread adoption of digital insurance tools and advanced analytics.
AI Is Becoming An Insurance Board Issue
Increasingly, the AI being used may not have been developed by the insurer at all. That changes the governance conversation.
For the last several years, conversations about artificial intelligence in the boardroom have largely centered on opportunity: Where can organizations automate? Where can they reduce costs? How can AI improve the customer experience? And, inevitably, what are competitors doing?
Those remain important questions. But for insurance boards, there is a more fundamental question that needs to come first: Do we actually know everywhere AI is being used in the organization?
That sounds simple. It isn’t.
Artificial intelligence is no longer confined to a technology department or a handful of sophisticated modeling applications. In insurance, it can touch underwriting, pricing, claims, fraud detection, customer service, marketing, data analysis and other business processes. Increasingly, the AI being used may not have been developed by the insurer at all.
That changes the governance conversation.
Undeclared AI is becoming cyber insurance’s blind spot
Cyber insurance leaders are increasingly viewing AI as an extension of existing technology risk rather than a new category that requires its own insurance product. But while insurers are not yet convinced that AI warrants a standalone policy, the growing use of tools that businesses fail to declare is creating a significant visibility challenge for the market.
The issue was discussed during KYND’s Cyber Drop webinar on 1 September, which brought together senior cyber insurance figures to build on the InsurTech company’s white paper, The Wild West of AI Risk. The panel broadly agreed that AI-related exposures can currently sit within existing cyber and technology errors and omissions (E&O) policies. One panellist described AI as the next stage of technology risk. Companies developing AI systems themselves could be a different case, however, as they may require dedicated cover for the risks created by the systems they build rather than simply the risks associated with using third-party tools.
Navigating AI’s Mass Personalization Opportunity in Insurance
We live in an era of significant generational, operational and technological change.
The useful life of everything new seems shorter than it once was, even as emerging capabilities continue to impress consumers. Yet not everything old is positioned for mass extinction. Properly cared for, technologies that are a generation or more old can remain useful for a surprisingly long time. Managing this bifurcation in technology environments is one of the more significant challenges facing IT organizations and their leaders today.
Just because you can replace something doesn’t mean you should. And while AI can produce impressive outcomes, it is not a cure-all, despite the hype. In some cases, it can create bigger problems than the ones it solves. The challenge is to use new and emerging technology in the right way, to solve the right problems.
Customer engagement and experience development offer an instructive use case. Recently, while trying to expand coverage with a Tier 1 P&C carrier, I was confounded by its AI-driven interface. My questions were complicated, and the desired coverages spanned multiple products. The experience had been designed for a simple use case. As I later discovered, the only way to talk to a human was to say, “I want to lapse these policies.” Like magic, the experience changed. Too late. By then, I really did want to lapse them, having found a regional carrier that was more than happy to talk with me.
Rob McIsaac is the President and CEO of RPM Ventures NC, LLC
Insurers Are Ready to Hand Repeatable Work to AI, Just 6% Would Trust a General-Purpose Model to Do It
New research finds that 83% of the global insurance market would hand repeatable work to AI; 75% will only allow AI to execute the work with an insurance-specific or governed model. Less than 1% of the market runs fully AI-native operations today.
The insurance market is ready to hand repeatable operational work to AI so it can win business it is currently turning away. A full 83% of the market supports AI executing repeatable work. A further majority, 75%, would only allow AI execution with a model built for insurance or governed inside their own rules. Both findings come from a report published today by ISG, the global technology research and advisory firm, and commissioned by mea Platform.
The study draws on senior leaders across underwriting, operations, claims, technology and transformation. It covers 20 operational activities, from submission intake and triage to quote generation, bordereaux processing, claims adjudication and compliance screening, across North America, Europe and Asia.
News
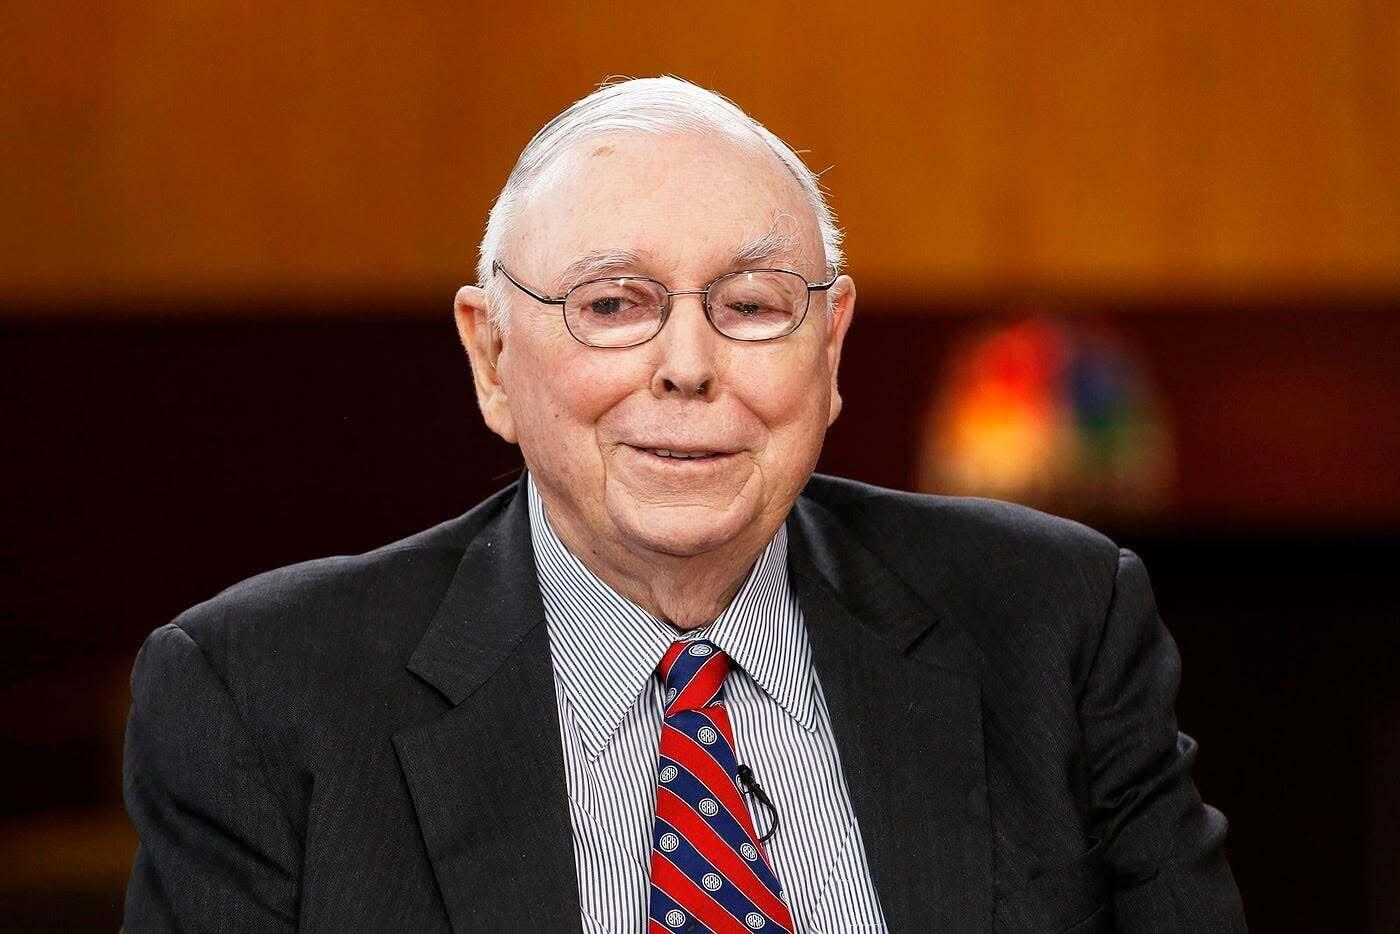
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — ‘All Intelligent People Do It My Way’
Insurance is one of those expenses that can feel particularly painful when nothing goes wrong, but it's often one of those things that can't be avoided. Not only is some insurance required by law, but it can also provide peace of mind in the event of something catastrophic.
Billionaire Charlie Munger, however, reached a point where he decided some risks just weren't worth insuring against. The longtime Berkshire Hathaway vice chairman had enough money to absorb certain losses himself, so why pay an insurance company to take a risk he could comfortably handle?
Munger explained his thinking at the Daily Journal Corporation's annual shareholder meeting in February 2023, only a few months before his death. He was asked about large companies that were choosing to self-insure against certain risks.
"In my own life, I'm a big self-insured and so is Warren," Munger said, referring to himself and Warren Buffett.
Financial Results
August 2026 Monthly Release
The Allstate Corporation (NYSE: ALL) today announced estimated catastrophe losses for the month of August of $748 million or $591 million, after-tax. Catastrophe losses for August include 21 events with approximately 50% of the losses related to one wind and hail event. Total catastrophe losses for July and August were $1.43 billion or $1.13 billion, after-tax.
Commentary/Opinion
Root: The Insurtech Has Finally Become An Insurer (NASDAQ:ROOT) | Seeking Alpha
Root, Inc. is rated Strong Buy as improving underwriting consistency and expense efficiency outweigh slower premium growth.
- ROOT has shifted from hypergrowth toward disciplined underwriting, prioritizing sustainable margins over aggressive premium expansion.
- H1 2026 net combined ratio improved to 91.7%, while the expense ratio fell to 27.6%, showing meaningful operating leverage.
- Distribution is diversifying through brokers, marketplaces, and embedded partnerships as ROOT reduces dependence on expensive direct customer acquisition.
- My central earnings scenarios imply $97–$114 million of post-tax income and roughly 40%–65% upside at a 12x earnings multiple.
- I upgrade ROOT from Hold to Strong Buy as improving underwriting consistency and expense efficiency outweigh slower premium growth.
State News
Additional action being taken to make property, casualty insurance more affordable
Additional measures are being taken to make property and casualty insurance more affordable, Gov. Greg Abbott said
The Texas Department of Insurance is responding to directives he issued two weeks ago it says, issuing a six-page memo stating its intent to comply and make recommendations to the legislature to consider.
Abbott has been issuing a series of directives to state agencies to find ways to reduce regulatory burdens and lower costs for Texans after costs have surged under three presidential administrations.
“The average annual homeowners’ insurance premium in Texas rose 79 percent in six years,” Abbott said. “High insurance costs hit Texas families hard,” which is why he directed TDI “to put consumers first, and TDI is taking action to do so. I will work with the Legislature next session to further curb premium increases.”
Regulation & Public Policy
Federal Legislation Targets Auto Insurance Fraud With Steep Penalties
Earlier this month, federal legislation was introduced to make motor vehicle collision fraud a federal crime, according to a joint press release by Congresswoman Laura Gillen (D-NY-04) alongside U.S Representatives Troy Nehls (R-TX-22), Josh Gottheimer (D-NJ-05) and Vince Fong (R-CA-20).
The bipartisan bill, Stop Auto Fraud Act of 2026, targets deliberately staged accidents intended to defraud insurance companies, imposing stiff penalties, including possible jail time, for violations.
“Long Islanders pay some of the highest car insurance rates in the country and ‘crash for cash’ schemes on our roads are driving rates even higher,” said Rep. Gillen. “When fraudsters stage car wrecks to scam their way to huge payouts, they’re putting lives at risk and forcing responsible drivers to bear the costs. I’m proud to lead this bipartisan bill to hold these criminals accountable, make our roads safer and lower sky-high car insurance costs.”
Research
2026 U.S. Home Insurance Study - JD Power
- High customer trust is linked to 3.0 times higher intended retention and 2.6 times lower shopping intent
- Overall satisfaction is 230 points higher among customers who strongly agree their experience is seamless
- When customers say communication channels are both easy and effective, future use intent increases to 95%
Rising home ownership costs and insurance rate pressure are adding affordability strain for homeowners, according to the JD Power 2026 U.S. Home Insurance Study,SM released today.
As customers more closely analyze household and insurance expenses, the study finds that trust, seamless service and channel effectiveness are critical to homeowners insurance retention and perceived value. High levels of trust are associated with 3.0 times higher intended retention and 2.6 times lower likelihood of shopping. Additionally, among customers who strongly agree their insurance experience is seamless, overall satisfaction is 794 (on a 1,000-point scale), compared with 384 among those who strongly disagree. Among customers who say their experience was not seamless, 25% say they received different or conflicting answers from different sources.
Claims
Finch Launches Industry-First Platform That Uncovers What's Buried in a Property Claim
Finch has launched the property claims industry's first full-claim intelligence platform, combining historical claim records, live inbox activity and analysis across the full life of a claim. The platform pulls together the entire universe of a claim, exposing what complexity conceals and turning it into usable intelligence.
The facts of a property claim are often scattered across thousands, and sometimes tens of thousands, of emails, documents, photographs and estimates. Large insurance carriers have the staff, data and technology to navigate even the most challenging claims. Policyholders and their representatives are left searching for answers. Finch is built to challenge that imbalance.
That tension is growing. Property claims are taking longer to resolve than at any point since 2008, according to J.D. Power's 2025 U.S. Property Claims Satisfaction Study. Following 27 catastrophic events in 2024 and 28 the year before, average repair times reached 32.4 days, while final payments took more than 44 days. Longer timelines can also mean larger claim records, as emails, photographs, estimates, supplements and other documentation accumulate over the life of a claim.
Podcast Sponsor
Audio Version - 'Connected: The Podcast' --- Sponsored by Pulse Podcasts
The ‘Connected’ Podcast by Alan Demers and in dedication of Stephen Applebaum, is a condensed audio version of the day's ‘Connected' newsletter, a daily scan of all the happenings in the world of Insurance & InsurTech News.
Pulse Podcasts: Introduce a new way for your audience to hear your voice! We are a podcast creation service that helps businesses turn their written content, like blog posts and news articles, into beautiful podcasts. Our platform writes the script, records the voices, and mixes the audio to create engaging content for your audience. It's affordable and has super-fast turnaround!
LISTEN AND SUBSCRIBE BELOW