
Cyber Risk
Cyber Insurance Demand Rises as Awareness Gaps Persist, Munich Re Finds
Interest in cyber insurance is rising among global C-level executives, but barriers to adoption remain, according to the Munich Re Global Cyber Risk and Insurance Survey 2026, as reported by Risk & Insurance.
The big picture: Munich Re found that awareness and product understanding are now barriers to cyber insurance purchases alongside price. Gaps in protection leave many organizations exposed to uncovered financial and operational losses when a cyber event occurs.
By the numbers:
- Buying intent: 43% of global C-level executives say their company is considering a policy and will very likely buy one, up from 35% in 2021.
- Barriers: Among respondents without coverage, 34% cited price, up from 27% in 2021. In 2026, 26% did not know cyber insurance existed, and 21% did not understand it, up from 15%.
- Offers by size: 33% of businesses with revenue of $1 million or less said commercial cyber insurance had ever been offered to them, vs. 65% of companies with revenue of $1 billion to $5 billion.
- Information source: 43% of C-level executives prefer to hear directly from an insurer, vs. 21% who favor a broker.
The New Cold War: Hackers Are Targeting Internet-Connected Freezers
When you hear the words “surprise attack,” maybe you think of Pearl Harbor. Or the Tet Offensive. Or 9/11. Or maybe you worry about a “dirty bomb” in an American city. You probably don’t think of French supermarkets. You probably should.
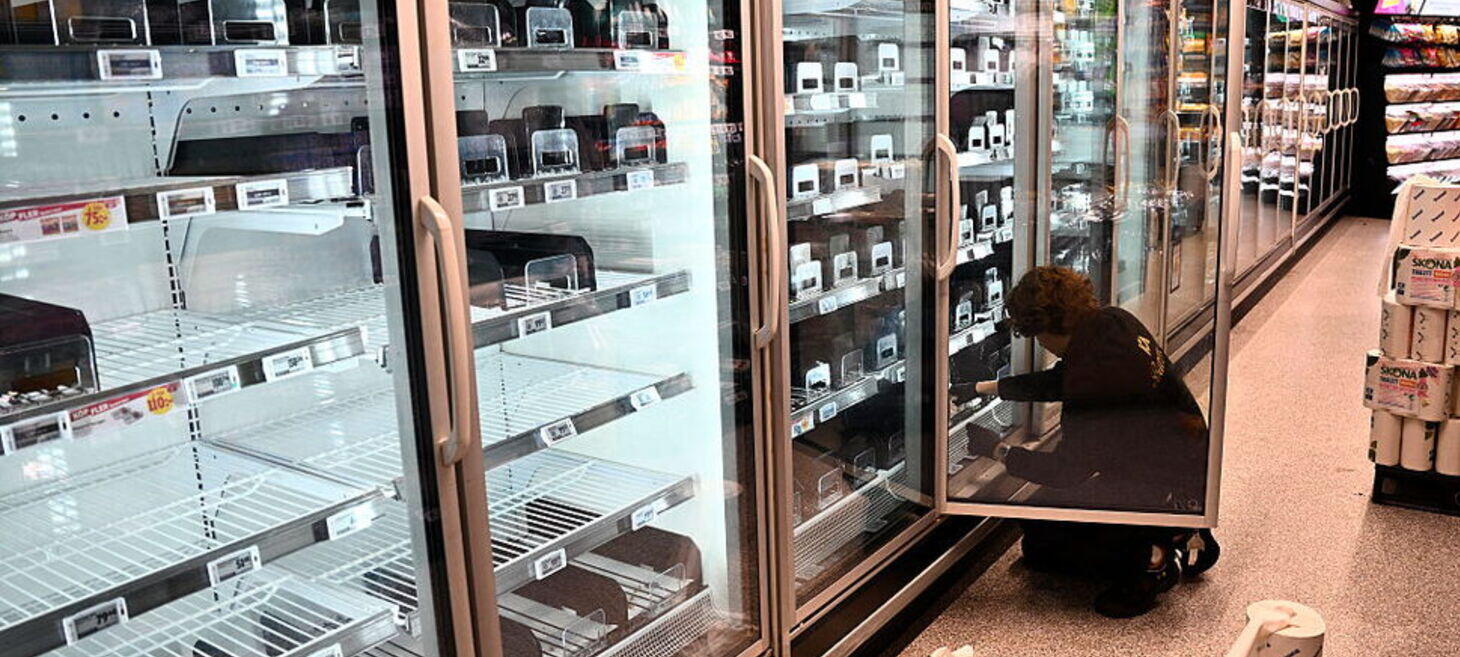
In mid-October, hundreds of such stores endured a cyberattack in which the hackers raised the temperature in freezers and cold storage rooms to 122 degrees Fahrenheit and delayed alarms that would normally alert supermarket workers to the problem. The result: millions of euros in spoiled food.
A second wave struck 10 additional European nations last week. Then came a similar assault on refrigeration equipment at France’s public blood transfusion operator, EFS – though that intrusion triggered backup alarms that let technicians leap into action before any blood products were compromised.
State News
Jane Kim’s plans to cut costs as CA insurance commissioner – NBC Los Angeles
Kim, endorsed by Sen. Bernie Sanders, ran the campaign as a progressive candidate who is seeking to overhaul the state’s insurance system.
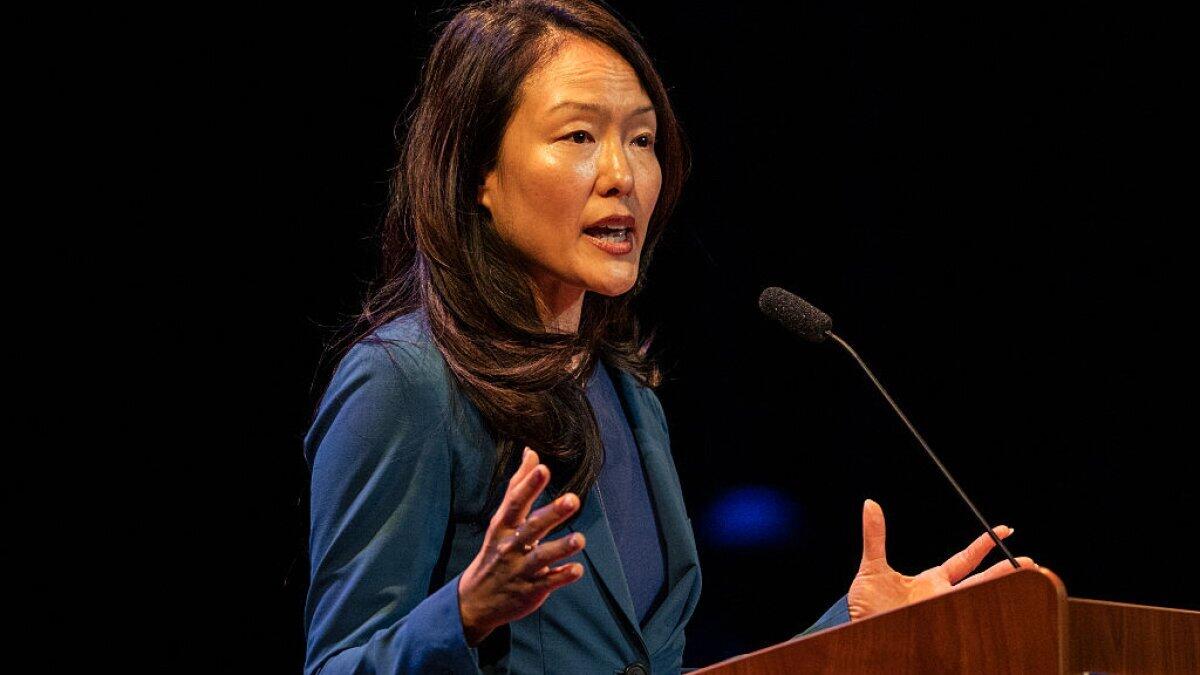
Jane Kim will win the race for California insurance commissioner, easily surpassing Southern California State Sen. Ben Allen by more than 600,000 votes, NBC News projected Monday.
Kim, who was endorsed by Sen. Bernie Sanders, ran as a self-described "unapologetic" and "populist" candidate seeking to overhaul the state's insurance system. Her proposals included creating a single-payer disaster insurance system and lowering other insurance costs for consumers.
"California shouldn't just be blue. We should be bold, and we will govern the way we ran, ambitiously with some big ideas," Kim said after declaring victory on social media.
Climate/Resilience/Sustainability
Roofing Manufacturers Challenge IBHS 15-Year Fortified Roof Limit
Asphalt roofing manufacturers are challenging a new Insurance Institute for Business and Home Safety (IBHS) requirement that limits Fortified roof recertification to roofs younger than 15 years, according to Insurance Journal.
The Asphalt Roofing Manufacturers Association (ARMA) criticized the research supporting the requirement, citing nonstandard testing methods, unrepresentative sampling, and incomplete modeling. The association also argued that the study did not adequately account for positive performance results or updated manufacturer installation guidelines.
New Fortified Requirement Takes Effect in 2027
- The IBHS requirement, announced Sept. 29, takes effect Jan. 1, 2027. It prevents roofs older than 15 years from maintaining Fortified certification, which can qualify homeowners for property insurance premium discounts.
- The requirement follows a decade-long IBHS study of shingles at testing sites nationwide and examinations of roofs following three windstorms.
- IBHS emphasized that the age restriction applies only to Fortified recertification. It does not establish the service life of asphalt shingles or determine whether individual roofs need replacement.
- The Fortified program has expanded through state-funded wind mitigation initiatives and building codes. In May, IBHS reported that more than 100,000 structures had earned the designation, double the number in 2023. Alabama accounts for more than half of those homes.
Commentary/Opinion
Insurance AI’s Next Test: Can Carriers Trust the Data?
Insurance companies are beginning to look toward the next phase of AI adoption with agentic AI and automation, according to Chris Newman, CEO of ACORD Solutions Group, at this year’s InsurTech Connect conference in Las Vegas.
However, as AI moves further into insurance decision-making and business operations, insurers need confidence in the data supporting the technology.
“I think AI undoubtedly is capable of making very good decisions and evolving things as we’re all seeing in businesses today,” he said. “But the challenge comes with the trust element in terms of can you trust your data.” ARTICLE
Autonomy in Insurance: Defining the Industry’s Next Transformation
Everyone in property/casualty insurance seems to agree on one key term right now: autonomy. But nobody defines it the same way.
It shows up in analyst reports, vendor pitches, board decks and innovation road maps. It gets conflated with automation, confused with AI and occasionally dismissed as the latest re-labeling of what the industry has been doing for a decade.
The vagueness has a consequence. Many autonomy initiatives end after the proof of concept and never reach production, held back by unclear benefits, skills gaps, regulatory compliance and cost. This is usually due to a narrow focus on tactical efficiency or technology demonstration, without a clear view of the business outcome or what the stakeholder experiences.
Automation enhances an existing process by increasing speed, consistency and efficiency, primarily by reducing manual touchpoints. Autonomy goes a step further by enabling the process to execute largely independently with minimal human intervention.
News
This two-year-old startup is reshaping a 129-year-old industry
OpenRoad Insurance is targeting the $15B collector car market with tech-first specialist coverage
On October 20, 1897, Travelers Insurance wrote the very first automobile liability insurance policy to Gilber J Loomis - a mechanic from Westfield, Massachusetts. And since then, the market has only accelerated in terms of size, scale and budget - especially where collectibles and classic cars are concerns.
OpenRoad Insurance only launched in 2024 but it’s now operating in a staggering 43 US states, eyes set on the opportunity to bring something new and innovative to an already established sector. Speaking to Insurance Business, Bryan Ballatore, Chief Marketing Officer at OpenRoad Insurance, explained that while the speciality car insurance sector is long-stablished, it’s also highly limited. And there’s room for a new player in the game.
Regulation & Public Policy
Intel Report: Nov 9, 2026 - Time Kills Deals: How to leverage speed as a competitive advantage
We’ve all seen them: cars flying down the highway at breakneck speed, weaving through traffic as if the rules of the road don’t exist. State officials even have a name for such drivers: super speeders.
Now there’s a growing push to harness GPS technology to slow them down. Virginia is pioneering the use of speed-limiters as an enforcement tool. Other states have similar plans to tackle a roadway scourge that the government says contributes to more than 10,000 deaths a year nationwide. Since Virginia’s program began in July, about 100 speed-limiters have been installed in cars.
Most users were charged with or convicted of reckless driving, often for topping 100 mph; installing the device was an alternative to license suspension. Think of it as speeding’s version of ignition-interlock devices, which force people convicted of DUI to pass a breathalyzer test to start the engine. One aims to stop drunken driving, the other egregious speeding. Virginia’s devices use GPS and a map database to determine speed limits—then prevent drivers from surpassing those limits even if they hit the gas. Limited overrides are permitted for merging or emergency maneuvers. The Wall Street Journal
Claims
AI and medical records: A six-point checklist for P&C insurers
In auto and liability, workers' compensation and disability insurance, the medical record drives what care is authorized, when the claimant returns to work and what the claim is worth.
Carriers, third-party administrators (TPAs) and self-insured employers now use artificial intelligence to review medical records, generate summaries and timelines, and flag issues and events. Courts are beginning to rule on how people use AI.
If your organization uses AI to review medical records, sooner or later, opposing counsel or a regulator will challenge that use — in a deposition, a bad-faith claim or a regulatory examination.
InsurTech/M&A/Finance💰/Collaboration
KKR to Hold 12.1% of Canopius in Acquisition
Canopius Group (“Canopius”, or the “Group”), a leading international specialty and P&C (re)insurer, today announces that Samsung Fire & Marine Insurance (“SFMI”) has entered into an agreement to acquire the remaining 60% stake in Canopius, alongside funds managed by global investment firm KKR, and Korea Investment Corporation (“KIC”).
The outstanding shares are being acquired from Canopius’ other existing shareholders, including Fidentia Fortuna Holdings, the controlling consortium led by global private investment firm Centerbridge Partners.
SFMI will acquire an additional 40.6% stake in Canopius out of the remaining 60%, increasing its total ownership to 80.6% through this transaction - KKR and KIC will hold 12.1% and 7.3% respectively. (The final shareholding is subject to minor adjustments at closing).
KKR intends to drive value creation and support Canopius’ continued growth by leveraging its global platform and operational, strategic, and M&A expertise.