
Legal System Abuse/Social Inflation
More than 20 states now regulate litigation funding: Triple-I
Triple-I says funding has helped add more than $230 billion to liability losses
More than 20 states have now passed laws requiring disclosure of third-party litigation funding (TPLF), according to a new issues brief from the Insurance Information Institute (Triple-I). Attention is now turning to federal courts.
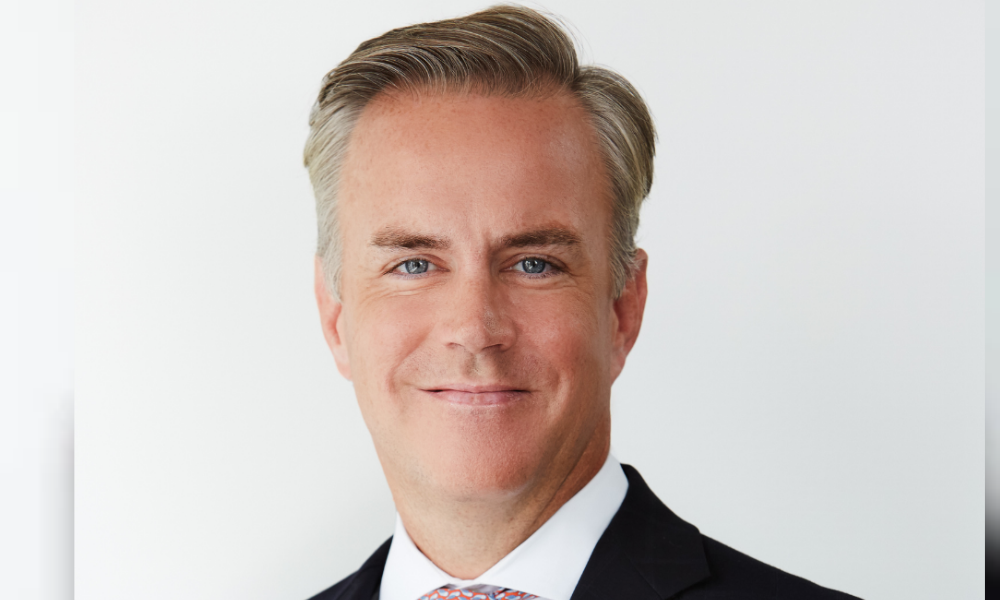
“Litigation funding has operated in the shadows for too long,” said Sean Kevelighan (pictured), Triple-I’s chief executive.
North Carolina goes furthest
North Carolina has taken the toughest approach so far. Its HB 315 bans litigation investment outright and allows civil penalties of up to $50,000 per violation. Triple-I said it was the first state to do so.
Financial Results
Chubb posts record $5.79bn P&C underwriting income for first 9M'26 - Reinsurance News
Chubb has reported record property and casualty (P&C) underwriting income of $5.79 billion for the first nine months of 2026, up 33.7% year on year, with a P&C combined ratio of 84%.
For the first nine months of 2026, Chubb’s gross premiums written increased 4.8% year on year to $52.86 billion, while net premiums written rose 5.1% to $43.85 billion.
Chubb’s net income before accounting for non-controlling interests was $7.97 billion for the period, compared with $7.45 billion a year earlier.
After the non-controlling interest adjustment, net income reached $8.02 billion, up from $7.1 billion in the same period of 2025.
Farm Bureau P&C insurers post first underwriting gain since 2021
U.S. farm bureau insurers saw positive momentum in 2025, as the property/casualty side reclaimed underwriting profitability, ending four consecutive years of underwriting losses, according to a new AM Best report. At the same time, their life/annuity counterparts, reported a growth in net premiums written in 2025 that bested the overall life/annuity industry’s growth - a first since 2016.
The Best’s Market Segment Report, titled, “US Farm Bureau Insurers Reverse Direction: P/C Profitable; L/A Premiums Up Slightly,” notes that momentum following the strong 2025 results has continued into the first half of 2026, as property/casualty farm bureaus recorded nearly $1 billion in underwriting gains in the first six months of 2026, on pace with the $2.9 billion in underwriting income posted for 2025. Prior to 2025, property/casualty farm bureaus had last recorded a full-year underwriting gain in 2020.
Progressive's Rising Auto Premiums Support Growth and Underwriting
PGR's rising auto premiums, expanding policy base and improved underwriting profitability support growth as competition intensifies in the U.S. auto market.
The Progressive Corporation PGR is benefiting from growth in its auto insurance business, where rising premiums and an expanding policy base are supporting premium growth and underwriting profitability. However, intensifying competition in the U.S. personal auto market is increasing the importance of disciplined pricing and risk selection.
In the third quarter of 2026, Progressive's net premiums written increased 4% year over year to $22.3 billion. In September, policies in force grew 6% to approximately 40.5 million. Direct auto policies rose 8%, while agency auto policies increased 7%, highlighting continued customer growth. Higher premiums can further support revenues as policies renew, provided rate increases adequately reflect claims inflation, repair costs and accident severity.
Commentary/Opinion
Insurance Companies Claim They Have to Hike Consumers’ Premiums. Their CEO Compensation, Dividends, and Advertising Costs Tell a Different Story
Auto insurance costs have increased 55% and a CFA report found that homeowners insurance costs increased by an average of 24% nationwide.
The insurance companies claim that they have to raise rates because of increased losses and risk, but their CEO compensation tells a different story.
CFA’s new release found that in 2025, executives at ten of the largest insurance companies earned over $155 million in total compensation.
And these figures are astonishing. To cite a few examples: in 2025 State Farm’s CEO earned $10.2 million, Liberty Mutual’s CEO earned $14.4 million, and Progressive’s CEO earned over $17 million—all three executive salaries went up from 2024. And the three companies that paid their CEOs the most: Nationwide paid its CEO $20 million, Allstate paid its CEO $22.9 million, and Travelers paid its CEO a little more than $24 million. In 2025, the median American household income was $87,460.
Climate/Resilience/Sustainability
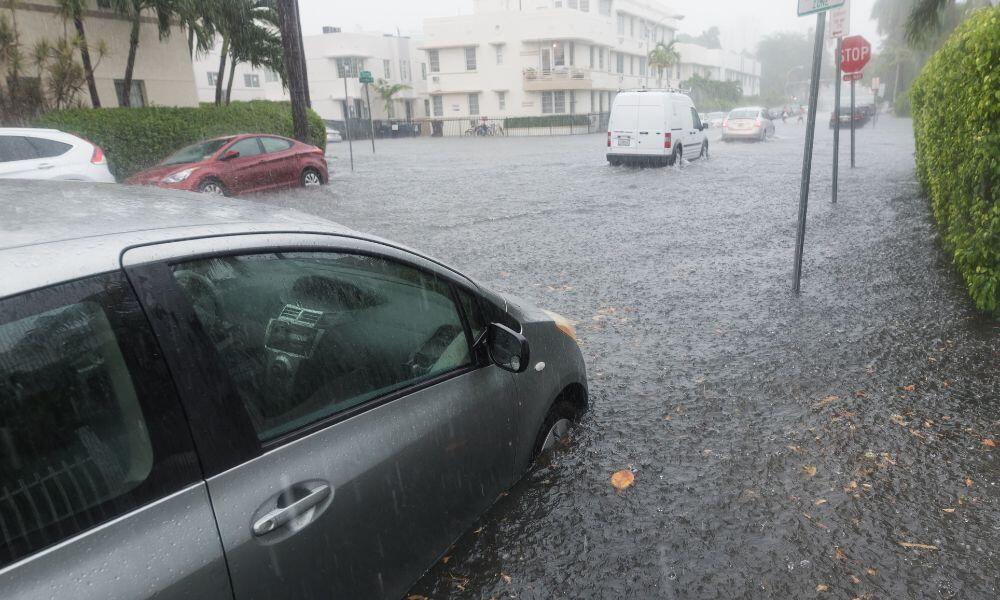
FEMA retreats from disaster response and launches a tool to sell flood insurance without brokers
FEMA administrator Cameron Hamilton told state emergency management leaders at a private conference in Little Rock, Arkansas that states must build their own financial reserves and capabilities to handle most disasters without federal help - with federal disaster aid cuts possible within six months.
"Every state must have the appropriate financial reserves and other abilities to ensure that recovery efforts can start immediately and not necessarily be held up simply because of the federal disaster declaration process," Hamilton said in remarks obtained by Politico. "A future that I hope we would shoot for is one where we wouldn't require as many disasters because the capability of states is so high and so substantial."
AI in Insurance
WR Berkley CEO Shares Insights on AI Adoption During Q3 Call
W.R. Berkley Corp. Chairman, President and CEO W. Robert Berkley, Jr. chose the third quarter of 2026 to enlighten analysts on the insurer’s journey parallel to society’s breakneck adoption of technological advances and its effect on the economy.
“My colleagues many, many years ago recognized the importance of data and how that role was going to become ever more greater,” he said in his opening remarks during a conference call to discuss Q3 earnings. “We have been on a data journey for many, many years at this stage. And fortunately for us, we are reasonably well positioned as we see many of the technology tools that are being brought to bear, AI-related in particular. Data is the fuel that drives those engines.”
'Saving time is not our ROI' - how US insurance firms are learning to measure tech investment
Jennifer Kessel draws a distinction that most technology vendors would prefer to avoid.
"I hear a lot of we're saving X amount of time," said Kessel, chief operating officer at USG Insurance Services, at a recent Insurance Business US Leaders Network transformation roundtable. "For us, that's not in our ROI. There's something attached to it, but that's an efficiency. What I'm really interested in is what are we doing with that gained time? What other value are we providing? And that's where I start calculating the ROI." FULL COMMENTARY
That reframing - from time saved to value created with that time - is the analytical shift most technology investments never make it to. It requires knowing not just what a process costs now, but what the organization does with the capacity automation returns, and whether that use of capacity shows up in revenue or client outcomes.
Who Structures the Problem in AI-Assisted Insurance Decisions?
The debate on “human in the loop” governance models for AI focuses heavily on who should make decisions, yet it often treats decision-making as something that happens at the end of the process. Structuring the problem occurs much earlier and is a key factor in making decisions.
In fact, the way we structure a problem has a disproportionate impact on how well we understand it and our likelihood of solving it. In this article, I’ll unpack why problem structuring is so important and why I believe that it is something users should own in high-risk, AI-assisted decisioning models. An insurance claim I once managed illustrates the point.
Unified Agentic Core: Insurance Core Modernization
AI is reshaping every industry, but insurance is especially exposed because it is among the most data intensive.
The question for COOs and CIOs is no longer what agentic AI can do but what decisions they must make to transform their core system so it’s capable of scaling and capturing the technology’s full benefits. It is a unique opportunity for insurance tech leaders to guide the agentic transformation, and choosing the right core modernization archetype is vitally important.
By now, most insurance companies are at least piloting agentic AI solutions. Many are starting to scale them, and a few industry leaders are already reaping clear, measurable benefits. Based on BCG experience, commercial property and casualty insurance, for example, can drastically cut underwriting cycles from 10 to 20 days to 1 to 2 days, while claims can benefit from a significant increase in straight-through processing of up to 70% to 90%, as well as contributing to material improvement in loss ratio. Given this potential, many industry leaders are looking for ways to incorporate agentic elements into the core. FULL REPORT
State News
Washington implements new claims-handling rules
Washington has implemented updated insurance claims-handling rules that establish more specific deadlines for insurer communication and investigations.
The rules took effect October 18 under Insurance Commissioner Patty Kuderer. These regulations have remained largely unchanged since their 1978 adoption, according to the Washington Office of the Insurance Commissioner (OIC).
"Most claims are processed without incident, but sometimes policyholders are left without a clear understanding of their claim's progress," Kuderer said in a release. "The new rules will maintain a fair claim environment for consumers and provide transparency into the process that affects their financial recovery."
InsurTech/M&A/Finance💰/Collaboration
Insurance agency M&A sinks to 8-year low as PE exits loom
Deal volume falls 19% through Q3 2026 as private equity platforms shift focus to exits and recapitalizations
Insurance agency mergers and acquisitions fell to their slowest pace in nearly eight years through the third quarter of 2026, as private equity-backed platforms pulled back from high-volume tuck-in buying and shifted focus toward integration and exits.
Firms announced 439 insurance agency acquisitions in the first three quarters of 2026, down 19% from the 539 recorded in the same period a year earlier, according to OPTIS Partners, a Chicago-based investment banking and financial consulting firm that tracks distribution M&A. The trailing 12-month deal count through September (600 transactions) has not been lower since the second quarter of 2018, when 578 deals were logged.